The AI Race Is Accelerating. Professional Services Will Benefit
Read more
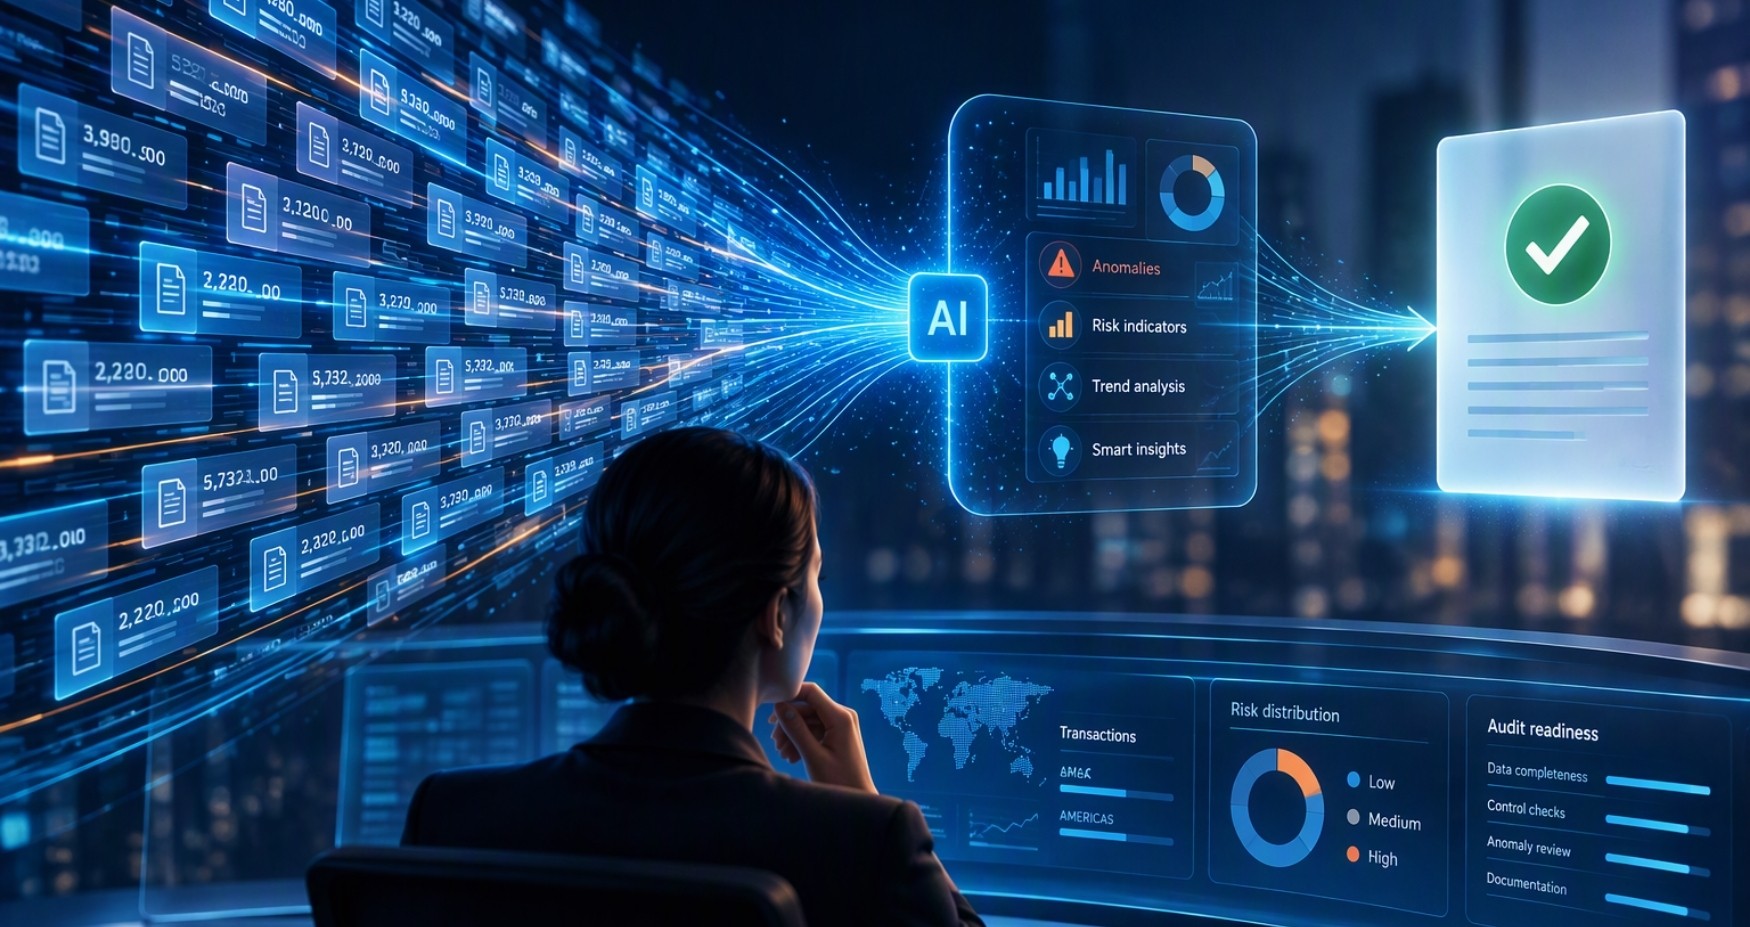
10,000 transactions. Three days. One audit conclusion. Where do you start?
Imagine this.
You have three days to examine 10,000 transactions across multiple systems. Some records don't reconcile neatly. Others look entirely routine.
And somewhere in that data could be an exception that changes your assessment.
What's your first move?
Which approach would you take?
Explore the trade-offs with audit analytics specialist Tariq Islam in our upcoming practical webinar, Beyond Sampling: How Data Analytics Can Strengthen Audit Assurance, on 22 October 2026 at 12:00–1:00 PM AEDT. Explore the webinar →
There isn't necessarily one right answer. Each approach has its place.
But the choice raises a bigger question: Are we spending too much time finding what to test, and not enough time investigating what matters?
Audit teams have access to more information than ever. Transaction histories, financial records and operational data can provide a much richer picture of risk.
Yet the practical constraints haven't disappeared.
Deadlines remain tight. Information sits across different systems. And auditors still need sufficient appropriate evidence to support their conclusions.
More data doesn't automatically mean better assurance.
In fact, without an effective way to analyse it, more information can simply mean more work.
Consider a transaction that looks perfectly ordinary in isolation. Its value falls within an expected range. Its description raises no immediate concern.
But what if the same supplier received multiple payments just below an approval threshold? Or transactions that appear unrelated share unusual characteristics when examined together?
These are the kinds of patterns that can be difficult to recognise when information is reviewed in isolation.
Traditional audit sampling remains an important and valid methodology. But it isn't the only way to examine a population.
Data analytics creates opportunities to look more broadly before deciding where detailed investigation is needed.
Instead of beginning with a limited selection, auditors can analyse larger datasets, identify unusual patterns and use those findings to inform their testing strategy.
The distinction matters.
The objective isn't necessarily to test more transactions. It's to make better-informed decisions about which transactions deserve attention.
And that requires more than running an exception report. Auditors still need to understand the reliability of the underlying data, investigate relevant findings and maintain a clear trail from source information to conclusion.
The next time you're confronted with thousands of records and a fixed deadline, consider these questions.
These questions point towards a different way of working: one where data helps direct audit effort rather than simply adding to the volume of information auditors must review.
Discover four practical shifts in audit analytics. Explore the webinar →
You still have three days.
You still need reliable evidence.
And you still need to exercise professional judgement.
But what if, before selecting your tests, you could identify unusual relationships, flag transactions that merit closer attention and gain a broader understanding of the population?
Would you approach the audit differently?
That's the discussion at the heart of Beyond Sampling: How Data Analytics Can Strengthen Audit Assurance.
Join Tariq Islam, Managing Director and Founder of RapidLynx Consulting, for a practical exploration of how audit teams can use analytics to identify risk, focus testing and strengthen assurance.
Drawing on his experience in audit analytics, including senior roles within internal audit at two of Australia's major banks and previous experience at PwC, Tariq will explore four practical shifts in how auditors work with data.
The session will also include a short Caseware-led example demonstrating how technology can support these approaches, followed by live Q&A.
22 October 2026 | 12:00–1:00 PM AEDT
For audit, risk and assurance professionals looking to get more value from the data they already have. Register now →
Because better assurance doesn't always begin with more testing. Sometimes, it begins with knowing where to look.